Skip Navigation or Skip to Content

3-Minute Read

3-Minute Read

Compounding Disasters Cause Compounding Premiums

Aug 15, 2024

Compounding Disasters Cause Compounding Premiums

A megatsunami, flood, volcanic eruption, and earthquake hit Earth in rapid succession, causing worldwide destruction. 

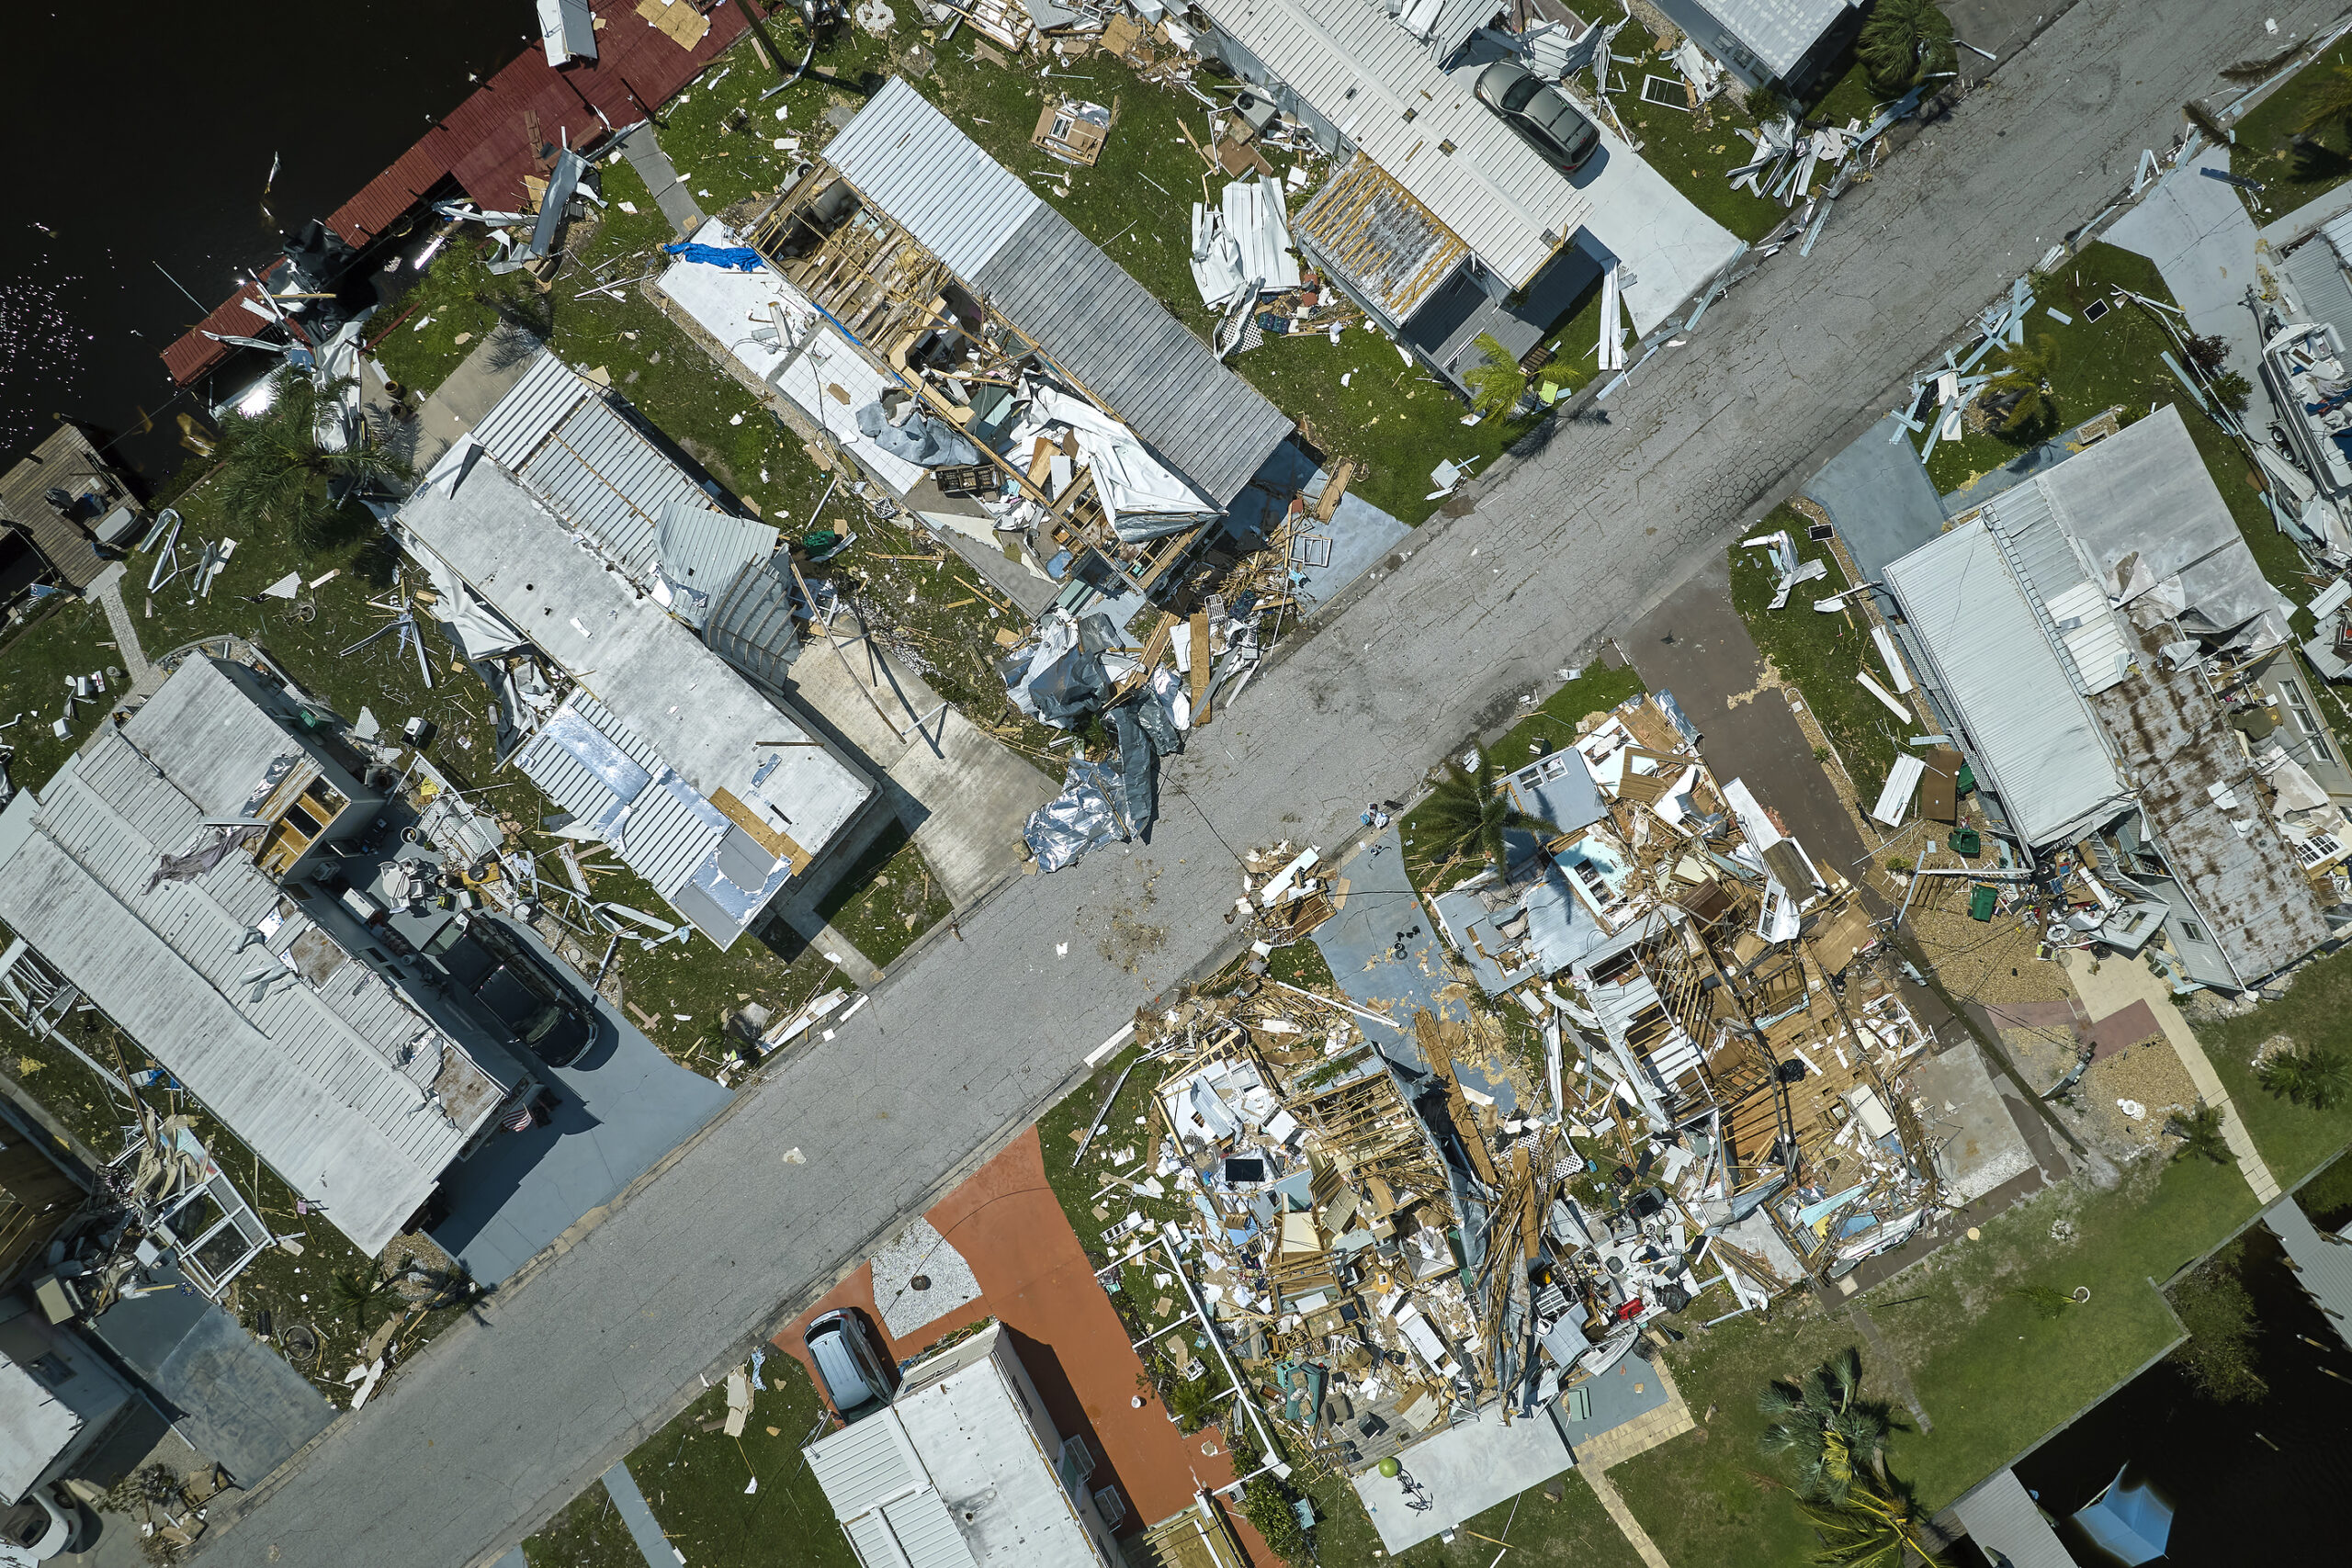
While this scenario is the fictional plot of the film 2012, today you would be forgiven for assuming that it’s a current headline. A recent report from the National Academies sheds light on the growing threat of compounding disasters — scenarios where multiple natural events occur simultaneously or in quick succession, leading to more severe impacts and complex recovery processes for commercial properties.

Impacts on the Insurance Industry

Compounding disasters mean compounding challenges for the property insurance market. If you’re an insurance agent with commercial clients in regions prone to natural disasters, staying informed about the latest trends in disaster management will help keep your insureds’ businesses protected — and may provide you with opportunities to offer them additional coverages. 

Increased Risk and Complexity

Compounding disasters, like a hurricane followed by flooding, can result in higher cumulative insured losses, which means more costly and more frequent claims payouts. Traditional risk models may be inadequate in predicting the likelihood and impact of multiple, overlapping disasters. Access to carriers with the most up-to-date modeling can help account for these complexities.

Claims Management Challenges

Handling claims from interconnected disasters requires more sophisticated assessment and coordination, potentially slowing down response times. By offering your clients products from carriers well-versed in severe weather events, they’re more likely to move through claims management systems with ease.

Pricing and Underwriting

As risk increases, insurers may need to adjust premiums to reflect the probability of severe losses, leading to higher costs for policyholders. This can also result in tighter underwriting criteria, making it more challenging for certain properties or businesses to obtain coverage. Finding the right partner with an extensive network and the ability to underwrite policies can help you offer clients the best coverage at the best cost.

Trust MiniCo for Multi-Peril Coverage

MiniCo’s expert program teams stay focused on trends that impact business owners as well as the insurance market. Our underwriters identified the growing risk of severe weather over a decade ago and responded by working with our carrier partners across our program portfolio to enhance existing coverages, innovate new programs such as MiniCo’s exclusive Wind/Hail Deductible Buyback coverage, and expand our ability to underwrite commercial properties in high-risk geographic locations. 

MiniCo’s expertise in program management, underwriting, binding authority, and claims extends to a wide range of industries, including self-storage, nonprofit and social services, agribusiness, artisan contractors and landscaping, and fine art and collectibles. Learn more about our 19 exclusive programs and contact our program underwriters for information, coverage details, risk management resources, and to get a quote.

Put Minico to Work For You

For more than 50 years, MiniCo has built specialty insurance programs for clients with unique risk exposures. Our dedicated program teams bring niche underwriting expertise to a portfolio of exclusive programs, from self-storage and agribusiness to professional liability, nonprofits, and everything in between. When you partner with MiniCo, you give your clients coverage customized to their industry and competitive in the marketplace, backed by underwriters who know their business.

Want to receive information from MiniCo on timely marketplace trends, hot new program launches, and valuable industry expertise that will set you up to win? Sign up to receive email communications.