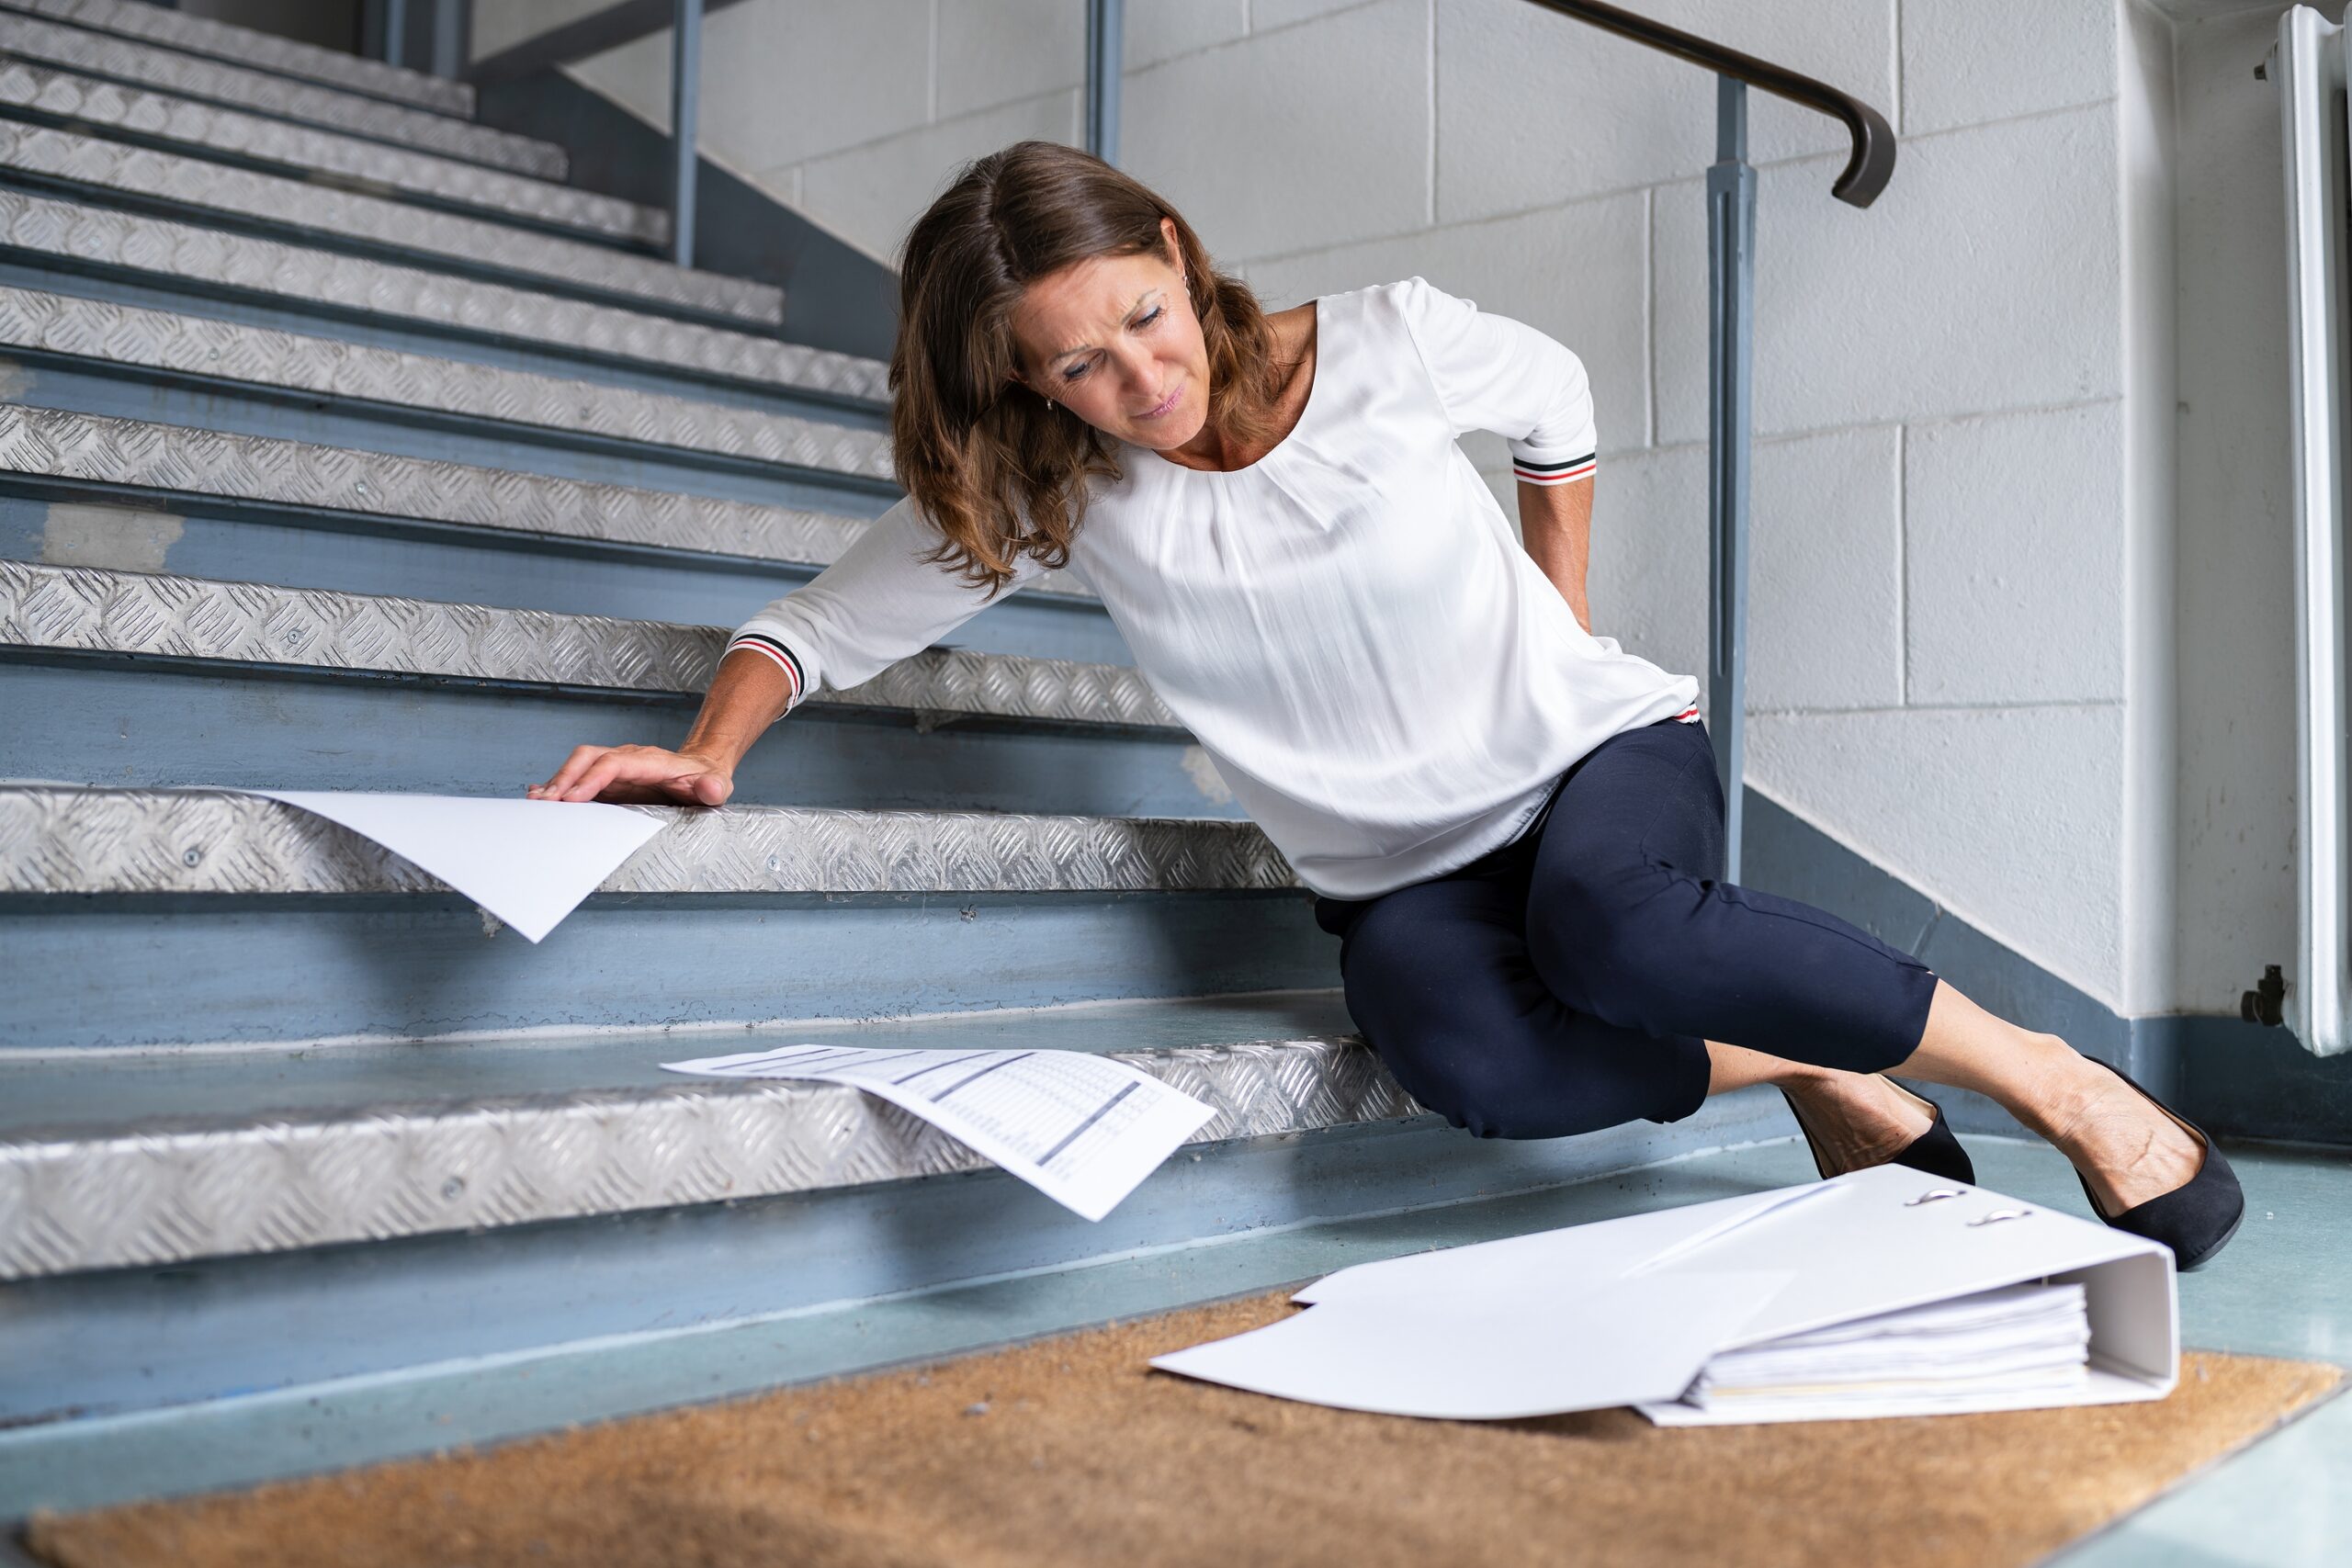
We’ve all seen the clip. Maybe it’s in a viral video, a sitcom rerun, or caught live at the grocery store. A worker rushes to clean up a spill, only to wipe out mid-stride and send a display of canned beans flying. It’s played for laughs, complete with dramatic flailing and a perfectly timed crash.
But offscreen, the consequences aren’t always so amusing. In real life, moments like this can lead to torn ligaments, broken bones, weeks of lost productivity, and six-figure claims. And while slips, trips, and falls might not grab headlines like major fires or storms, they’re among the most frequent—and most expensive—workplace injuries.
According to Liberty Mutual’s 2024 Workplace Safety Index, falls on the same level cost U.S. employers nearly $10 billion annually. And even slips and trips that don’t result in a fall rack up another $2.34 billion. These aren’t rare freak accidents. They’re routine, repetitive, and in many cases entirely preventable.
When a “Minor” Fall Isn’t Minor at All
In Travelers’ recent analysis of workers’ compensation claims, slips, trips, and falls ranked second in overall injury frequency, but first in severity. These are the injuries that lead to extended medical leave, surgeries, long-term disability, and six-figure settlements. The kind that upend operations for months, and they’re not confined to one industry:
- Construction: Falls on the same level jumped to the third most costly cause of loss.
- Healthcare and Social Assistance: These injuries overtook overexertion as the number one driver of claims.
- Wholesale Trade, Manufacturing, and Retail: All saw increases in both frequency and cost.
Even sectors that seem “low-risk” aren’t off the hook. Consider self-storage: a customer tracks in water on a rainy day, an employee steps on a loose mat, or uneven pavement trips someone near the loading dock. These are everyday scenarios that can lead to life-changing injuries.
Why Workplace Safety Training (Still) Works
One of the more hopeful findings in the sea of data? Prevention efforts work, and they don’t have to be complicated. A NIOSH-backed study of over 17,000 food service workers found that providing five-star-rated slip-resistant shoes reduced slip-related claims by 67%, which is a remarkably simple intervention with a measurable impact. Other high-impact strategies include:
- Regular floor maintenance and housekeeping
- Adequate lighting (especially in outdoor or transitional spaces)
- Using walk-off mats and signage
- Creating a culture where reporting hazards isn’t just encouraged—it’s required
Even the most high-tech workplace injury program will fall short if basic walking surfaces aren’t safe. That’s why OSHA’s walking-working surfaces regulation remains a frequent source of citations, with many carrying penalties well into six figures.
The Agent’s Role: Prevention, Framed as Protection
Every workplace has its hazards. But when those workplace hazards are predictable—and preventable—it’s up to insurance professionals like you to help connect the dots. A single fall can cost hundreds of thousands of dollars, yet the solution might be as simple as a new pair of shoes, a better mat, or one honest conversation.
That’s where MiniCo can help.
We understand the unique risks that come with operating a self-storage facility, running a nonprofit, providing in-home care, or managing a team of tradespeople. Our programs are designed around the realities your clients face every day, on wet floors, uneven ground, stairwells, and shop floors. With decades of experience, a dedicated underwriting team, and deep industry specialization, MiniCo offers risk management resources and expertise to help your clients stay prepared, protected, and profitable.
Let’s keep your clients on solid ground—together. Contact MiniCo for more information.
Explore Further
Help Your Clients Plan Ahead with Youth Sports Insurance: MiniCo’s Injury Response Playbook
Jun 18, 2026
When Coaching Standards and Risk Management Converge
Jun 11, 2026
2026 Insurance Claims Trends Agents Need to Know Now
May 21, 2026
Filing a Commercial Property Insurance Claim: 3 Tips From Claims Adjusters
Feb 12, 2026
Pickleball Injuries: Why Clubs, Leagues, and Schools Need Participant Accident Insurance
Jun 20, 2025
Injury Time-Out: Why Sports Camps and Event Organizers Need Participant Accident Insurance
Jun 12, 2025
School of Risk: Mitigating Lawsuits Against Schools
Jun 5, 2025
Travel Risk Assessments: Proactive Protection for Employees on the Move
Nov 28, 2024
On the Road Again: Top Business Travel Trends and Risks
Nov 21, 2024
Covering the Bases: Protecting Club Sports with Participant Accident Insurance
Nov 14, 2024
Protecting Participants: The Importance of Comprehensive Accident Insurance
Nov 7, 2024
5 Ways to Mitigate Wind and Hail Damage Risks for Your Insureds
May 16, 2023
Recent Posts
Why Small Businesses Need Cyber Liability Insurance More Than Ever
Aug 6, 2026
Cybersecurity Travel Tips for Agents to Share This Summer
Jul 23, 2026
Why Insurance Program Administrators Are a Strategic Advantage for Agents
Jul 16, 2026
Navigating the 2026 Wildfire Season: What Agents Need to Know
Jul 9, 2026
A “Below-Normal” Hurricane Season Is Not a Free Pass
Jun 25, 2026
Help Your Clients Plan Ahead with Youth Sports Insurance: MiniCo’s Injury Response Playbook
Jun 18, 2026
Explore Industry Topics
- Adult Residential Facility Insurance
- Agribusiness Insurance
- Allied Health Insurance
- Artisan Contractors Insurance
- Contractors Liability Insurance
- Cyber Insurance
- Equipment Breakdown Insurance
- Hired & Non-Owned Auto for Food/Cannabis Couriers
- Landscaping Insurance
- Miscellaneous Professional Liability Insurance
- News and Announcements
- Nonprofit and Social Services Insurance
- Participant Accident Insurance
- Professional Liability Insurance
- Risk Management
- Self-Storage Commercial Insurance
- Self-Storage Tenant Protection Plan
- Wind & Hail Deductible Insurance
Put Minico to Work For You
For more than 50 years, MiniCo has built specialty insurance programs for clients with unique risk exposures. Our dedicated program teams bring niche underwriting expertise to a portfolio of exclusive programs, from self-storage and agribusiness to professional liability, nonprofits, and everything in between. When you partner with MiniCo, you give your clients coverage customized to their industry and competitive in the marketplace, backed by underwriters who know their business.
Want to receive information from MiniCo on timely marketplace trends, hot new program launches, and valuable industry expertise that will set you up to win? Sign up to receive email communications.